One serious accident can exceed your auto or home liability limits. A personal umbrella policy adds $1 million or more in protection for your savings, home, and future income, often for a few hundred dollars a year.
Medical bills and legal judgments after a serious car accident or injury on your property can climb well past standard policy limits. When that happens, you could be personally responsible for the rest. An umbrella policy sits on top of your auto, home, and boat coverage to close that gap.
Additional coverage when injuries or property damage from an at-fault car accident exceed your auto policy limits, including accidents involving teen drivers in your household.
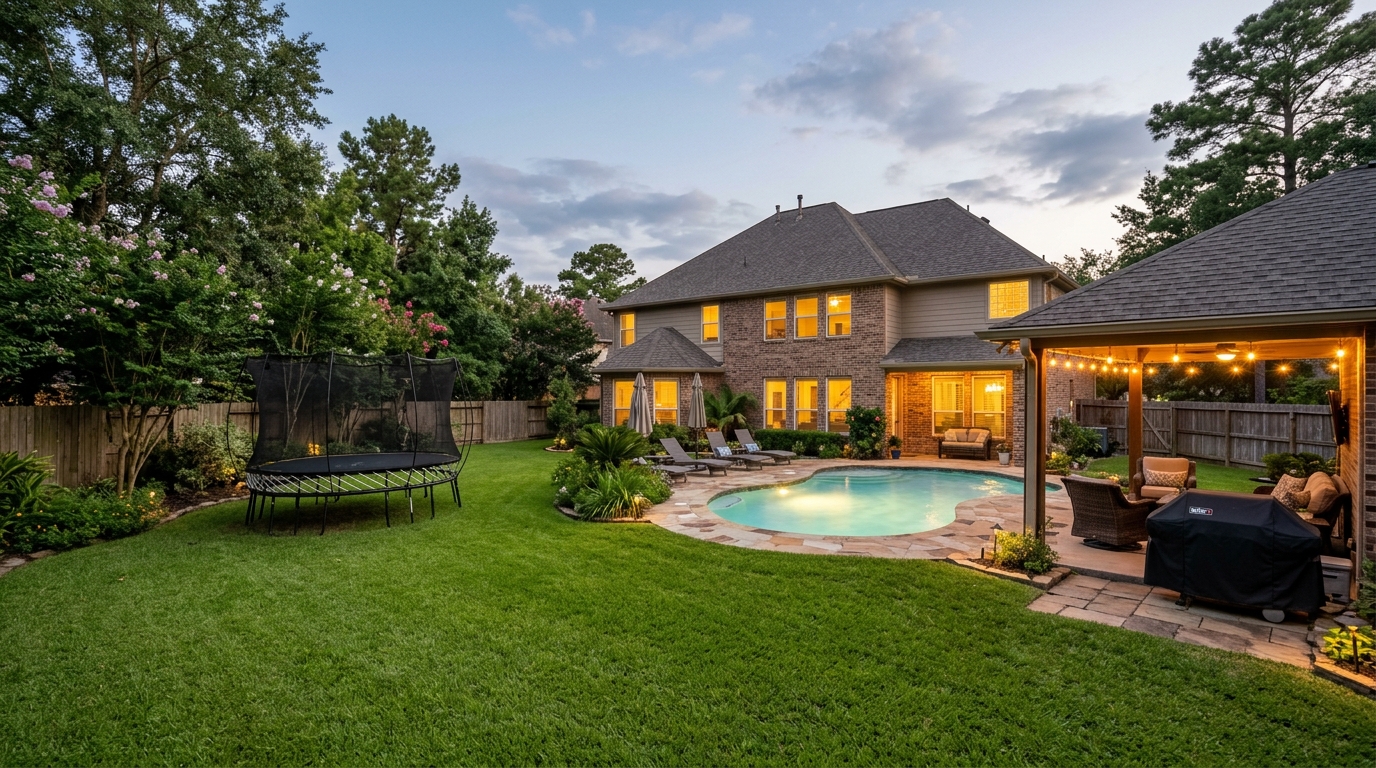
Protection for injuries on your property, such as pool accidents, trampoline injuries, dog bites, or guest falls, that go beyond your homeowners liability limit.
Attorney fees and court costs for covered claims, which can be substantial even when you're not found at fault.
Many policies include coverage for claims such as libel, slander, and defamation. Details vary by carrier.
Umbrella coverage can extend over boat liability and rental property liability when those policies are scheduled underneath.
We Compare Rates Across 15+ Top-Rated National Carriers
As an independent agency in Oxford, MS, we shop the market to find you the strongest policy at the lowest premium.
Common questions about personal umbrella liability coverage in Mississippi.
Umbrella insurance is extra liability coverage that kicks in after your auto, home, or boat policy's liability limits are used up. If you're found responsible for a serious accident or injury and the damages exceed your underlying policy, your umbrella policy helps pay the difference, plus legal defense costs.
Umbrella coverage is one of the most affordable ways to add serious protection. A $1 million personal umbrella policy often costs a few hundred dollars per year, depending on how many homes, vehicles, and drivers you have. We'll quote options from multiple carriers so you can compare.
Anyone with assets or future income to protect should consider one. It's especially important if you own a home, have teen drivers, own a pool, trampoline, or dog, own rental property, have a boat or ATVs, coach youth sports, or have a public profile in the community.
Yes. Most umbrella carriers require minimum underlying liability limits, commonly around $250,000/$500,000 on auto and $300,000 on homeowners. Requirements vary by carrier, and we'll help you align your policies so there are no gaps.
Beyond higher limits, many umbrella policies extend coverage to certain claims your base policies may not, such as libel, slander, and defamation, and may cover you worldwide. Coverage details vary by carrier, so we'll walk you through exactly what each policy includes.